
Filing an insurance claim is not simply a matter of reporting damage and waiting for payment. A successful claim depends on prompt notice, careful documentation, cooperation with the insurer, and a clear understanding of what the policy actually covers.
For residents of Wilmington, DE, claims may involve storm damage, frozen pipes, roof leaks, vehicle collisions, water intrusion, theft, fire, or medical treatment. The process is generally similar, but the details depend on the type of insurance and the policy language.
What should be done immediately after a loss?
The first priority is safety. Leave an unsafe structure, seek medical care for injuries, and contact emergency services when necessary. Insurance paperwork should come after immediate risks have been addressed.
Once the situation is safe:
- Prevent additional damage when reasonably possible.
- Turn off water, electricity, or gas if doing so is safe.
- Cover broken windows or damaged areas temporarily.
- Move undamaged belongings away from water or other hazards.
- Keep receipts for emergency supplies, temporary lodging, food, transportation, or repairs.
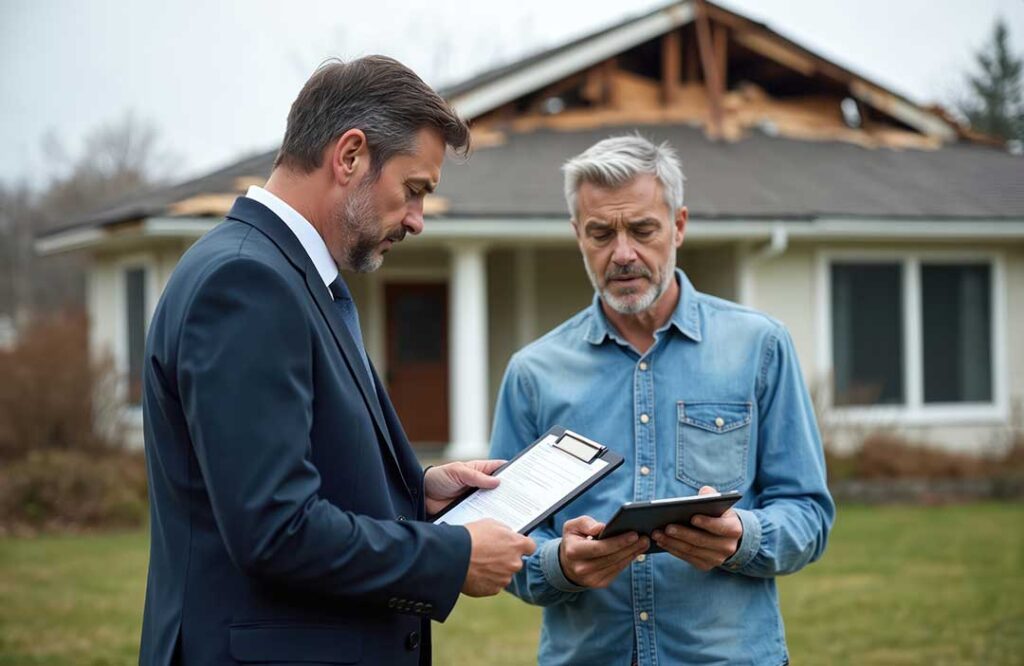
Temporary steps are usually appropriate, but permanent repairs should generally wait until the insurer has had a fair opportunity to inspect the damage. For example, replacing an entire roof or removing all damaged materials before photographs and an inspection may make it harder to establish the original condition.
If emergency work is necessary to protect people or prevent worsening damage, take photographs first when possible and keep detailed records of what was done.
How quickly should an insurance claim be reported?
Report the loss as soon as reasonably possible. Policies often require prompt notice, and delays can create questions about whether the damage worsened because action was not taken sooner.
The first report does not need to contain a complete estimate. Provide the basic facts:
- Date and approximate time of the loss
- Location of the damage or incident
- Type of event, such as wind, fire, theft, collision, or water leak
- Whether anyone was injured
- Temporary measures already taken
- Contact information and the best way to reach you
Ask for a claim number, the name of the assigned adjuster, and instructions for submitting photographs, receipts, repair estimates, police reports, medical records, or other documents.
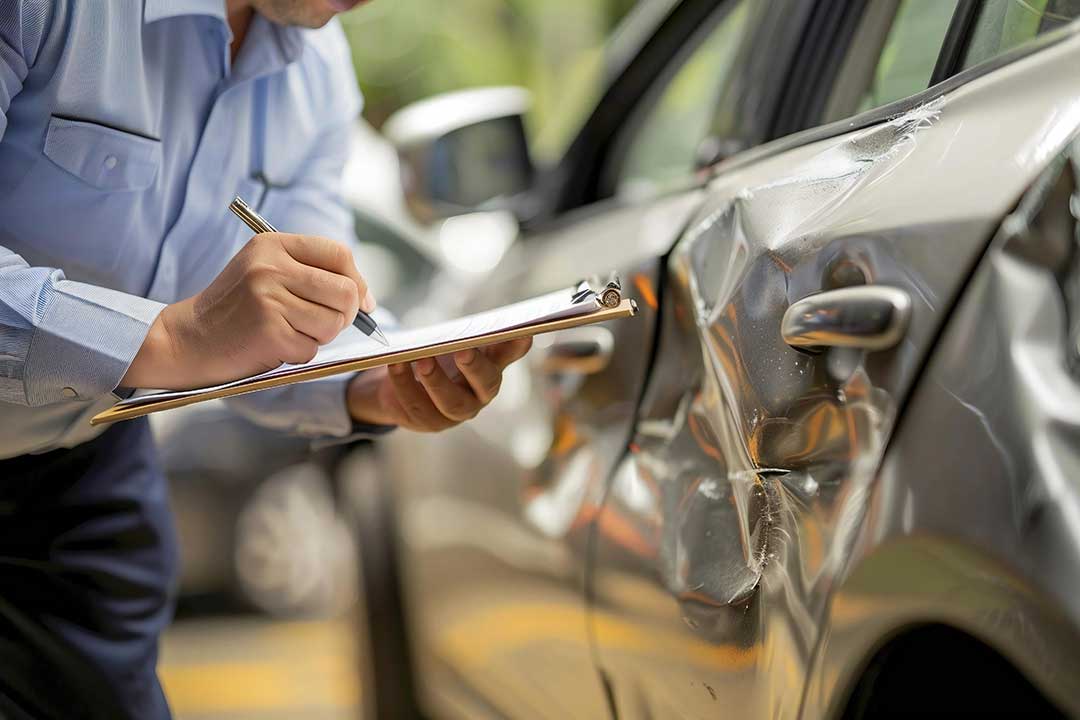
For auto claims, report the collision even if the damage initially appears minor. Some problems, including alignment issues or hidden mechanical damage, may not be visible immediately.
What documents and evidence help support a claim?
A claim is easier to evaluate when the evidence is organized and tied to specific items. Take wide photographs showing the location and close-up photographs showing the details. Include photographs of surrounding areas that were not damaged when they help establish the extent of the loss.
Keep copies of:
- Photographs and videos
- Receipts and invoices
- Contractor or repair estimates
- Police or incident reports
- Medical bills and treatment records
- Proof of ownership, such as purchase records or warranties
- A room-by-room inventory of damaged or missing property
- Written communications with the insurer
- Notes from telephone calls, including dates, names, and subjects discussed
For household contents, describe each item, its approximate age, condition before the loss, and replacement cost. A vague list such as “electronics” or “clothing” is less useful than an itemized description.
Residents in older homes, row homes, apartments, and densely developed neighborhoods may face damage that spreads between adjoining structures or affects shared systems. Document where the problem began, which areas were affected, and whether another property owner, landlord, association, or utility may also be involved.
How can the policy be used effectively?
Read the declarations page first. It identifies the covered property, coverage limits, deductibles, and policy period. Then review the sections describing covered causes of loss, exclusions, additional coverage, and duties after a loss.
A deductible is the amount paid by the policyholder before covered insurance payments begin. If damage is estimated at $8,000 and the applicable deductible is $1,000, the initial calculation may be based on $7,000 before other policy terms are applied.
Common coverage questions include:
- Is the cause of damage covered?
- Is the damaged property insured?
- Does a limit apply to jewelry, computers, tools, business property, or other items?
- Is replacement cost available, or is payment based on actual cash value?
- Are temporary living expenses covered?
- Does a separate policy apply to flood, earthquake, or another excluded risk?
- Are there deadlines for submitting forms or supporting documents?
A standard homeowners policy does not automatically cover every type of water-related damage. A burst pipe inside the home may be treated differently from rising water or groundwater entering from outside. The source of the water matters.
What should be expected from the insurance adjuster?
An adjuster investigates the loss, reviews the policy, estimates damage, and communicates the insurer’s position. The adjuster may inspect the property, request documents, ask questions, or provide forms such as a proof-of-loss statement.
Answer questions accurately and avoid guessing. If a fact is unknown, say so and provide the information later. Do not discard damaged property until the insurer has approved disposal or it presents a health or safety hazard. If disposal is necessary, photograph it thoroughly and preserve samples or identifying information when practical.
An insurer’s first estimate is not necessarily the final amount. Review it line by line. Look for missing rooms, damaged materials, labor charges, code-related work, debris removal, temporary repairs, and coverage limits.
The policy may require the policyholder to obtain estimates or submit additional proof. Those requirements should be followed carefully, while retaining copies of everything submitted.
What if the claim is partially paid or denied?
A denial or partial payment should identify the policy basis for the decision. Request a written explanation if the reason was provided only by telephone. Compare the explanation with the policy language and the evidence supporting the claim.
Common reasons for disputes include:
- The insurer believes the damage resulted from wear and tear rather than a covered event.
- The policy excludes the cause of loss.
- The amount of damage falls below the deductible.
- The insurer did not receive enough documentation.
- The property is subject to a special limit.
- The insurer believes repairs occurred before inspection.
- The claim was reported after a required deadline.
A disagreement does not automatically mean the insurer acted improperly. It does mean the decision should be reviewed carefully. Submit a written response that identifies specific items in dispute and includes supporting photographs, estimates, receipts, expert reports, or policy provisions.
Keep communication factual and organized. A clear timeline is often more persuasive than a long emotional description.
What deadlines should Wilmington residents watch?
Insurance policies and state law may contain different deadlines for reporting a loss, submitting proof of loss, appealing a decision, completing repairs, or bringing legal action. These periods can vary by policy and claim type.
Do not rely on a general internet deadline. Check the policy, claim correspondence, and any written notice from the insurer. Ask the insurer to identify applicable deadlines in writing.
For health insurance, filing and appeal deadlines can be especially strict. Review the explanation of benefits and the policy’s appeal instructions. Confirm whether a healthcare provider submits the claim or whether the patient must do so.
If a claim remains unresolved, policyholders may seek help from the Delaware Department of Insurance’s Consumer Services Division. That process does not replace a legal review when a lawsuit deadline or significant coverage dispute is involved.
How can claim problems be avoided before they happen?
Preparation makes the process faster and reduces disagreements. Keep a current home inventory with photographs, model numbers, receipts, and approximate purchase dates. Store copies of the policy and inventory somewhere accessible even if the home is damaged.
Review coverage after renovations, major purchases, changes in household members, home-based work, or the acquisition of valuable personal property. Also confirm whether flood or other separate coverage is needed for the property’s conditions.
After a storm or winter freeze, inspect for damaged shingles, fallen branches, frozen pipes, basement water, and interior staining. Early documentation can distinguish a new loss from older maintenance issues and can help prevent a small problem from becoming a larger one.
A successful claim is usually built on three things: prompt reporting, accurate documentation, and careful attention to the policy’s requirements.